YNAB
ynab.comFinanceVerified
- 4.58K Reviews
- 4.5
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When I first tried You Need a Budget (YNAB), I was looking for a way to make everyday spending feel less accidental. It is a finance app from ynab.com built around planning what your money should do before it disappears into a string of small purchases. That approach is more hands-on than simply checking a balance or reviewing a list of transactions, and it suits people who want to make deliberate choices rather than just observe past spending.
Starting with a clearer picture
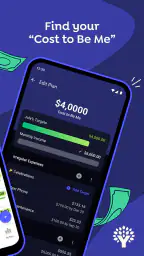
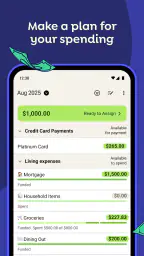
My most useful first step was not connecting anything or setting an ambitious savings target. It was listing the expenses I already knew were coming: rent, groceries, transport, bills, and a few irregular costs that always seemed to arrive at the wrong time. With a plan in view, I could see which dollars already had a purpose and which ones were genuinely available. That distinction is the heart of the experience, and it makes the app feel different from a basic expense tracker.
The idea is simple, but it asks for participation. I have to make decisions about priorities instead of expecting a chart to tell me whether I behaved well. When a new expense appears, I can consider what matters most and adjust the plan. That makes YNAB particularly useful for someone whose income is steady but whose spending tends to drift, or for anyone trying to prepare for irregular bills without pretending those bills are surprises.
Getting Started with YNAB
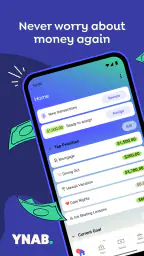
The first thing you'll notice when you fire up YNAB is its clean and straightforward interface. I appreciate an app that doesn't overwhelm me with too many bells and whistles. Setting it up was a breeze. After signing up, I was prompted to link my bank accounts. Don’t worry, it's secure, and your data is protected. I like that YNAB doesn't just track spending; it makes you plan for every dollar. It's all about giving every dollar a job, which is a game-changer for someone like me who tends to overspend.
Features That Stand Out
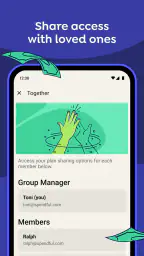
One of the standout features is the real-time syncing. I can be out shopping, make a purchase, and see the impact on my budget immediately. It's super convenient to have my partner on board too, as the app syncs across devices. No more awkward "I thought we had more money in that category" conversations.
That shared view is most valuable when it changes a decision before money is spent. For example, if my partner and I are shopping for groceries and one of us wants to add something extra, checking the relevant category gives us a practical answer: is there room, or should we move money from somewhere else? The useful habit is to treat the plan as a conversation, not a set of rules one person imposes. If we agree to shift funds, the budget stays realistic instead of becoming a record of what we hoped would happen.
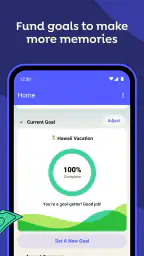
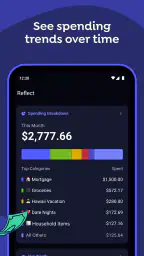
Another cool feature is the goal setting. Whether you're saving for a vacation, a new gadget, or just trying to pay off debt, YNAB helps you track your progress. It's like having a financial coach in your pocket. Plus, the reporting feature gives me a bird's-eye view of my spending habits, which is both enlightening and a little shocking at times!
Other Stories to Read




I find goals most helpful when I give them a clear place in the monthly plan. A future trip can feel abstract when it is only an idea; setting aside money for it makes the trade-off visible alongside routine expenses. The same logic can help with annual or occasional costs: instead of treating a renewal or a repair as a sudden setback, I can make room for it over time. This is a practical strength of a forward-looking budget, though it depends on checking in often enough to keep those priorities current.
Learning Curve and Community Support
I won't lie; there was a bit of a learning curve initially. YNAB isn't just about logging what you spend, but about planning ahead. It took me a week or so to get the hang of it. Thankfully, the YNAB team offers loads of tutorials, webinars, and a super supportive community. I found their blog and forums to be full of tips and tricks from fellow users. It's comforting to know I'm not alone on this budgeting journey.
The adjustment is less about learning buttons and more about changing the order of operations. A conventional tracker usually asks, “What did I spend?” This method asks, “What does the money I have need to cover?” That can feel uncomfortable if I am used to treating an account balance as permission to spend. I have to look at the plan before deciding whether a purchase fits, then revise it when life changes. If I want a passive overview with almost no upkeep, this routine may feel like too much work.
Making the routine work in everyday life
A realistic day might start with checking the plan before ordering lunch or making a quick household purchase. Later, when a transaction appears, I can make sure it belongs in the right category and compare the category balance with what I expected to spend. If the purchase was larger than planned, I can decide which other priority should give way. That small handoff—from a real-world purchase to an updated plan—is where the app’s approach becomes useful. It turns a vague sense of “I should be careful” into a specific choice.
For less predictable income, the same principle can be useful but requires more patience. I would first cover the essentials that need attention now, then assign what remains according to the next priorities. A budget built around money already available is easier to trust than one based on optimistic guesses about future pay. On the other hand, anyone who wants automatic forecasts to make decisions for them may prefer a simpler tool or a spreadsheet they can shape around their own method.
The app is free to download, and its in-app purchases range from $14.99 to $109.00 per item. I would factor that ongoing cost into the decision rather than assuming a budgeting app automatically saves money. Its value depends on whether the planning habit helps me make better choices than I would with a free spreadsheet, a bank’s spending categories, or a lightweight tracker. Those alternatives can be perfectly adequate if I only want to review transactions; YNAB makes more sense when I want to actively assign and adjust money.
Personal Experience and Insights
Since using YNAB, I've noticed a significant change in my spending habits. I’m more aware of my financial goals and am actually excited to see my savings grow. The app encourages you to live on last month's income, which has been a real eye-opener for me. It’s like having a buffer that gives me peace of mind.
That buffer is a worthwhile destination, not a requirement for getting started. I would not wait until my finances feel tidy before making a plan; beginning with the money currently available is more useful than trying to build an ideal budget in one sitting. As the habit settles in, the longer-term aim can help reduce the pressure of timing every bill against the next payday. People with irregular earnings may need longer to reach that kind of cushion, but the underlying practice of prioritizing what is on hand still applies.
One thing I love is that YNAB doesn’t guilt-trip you for spending. It's realistic and understands that life happens. Instead of feeling bad about a splurge, you just adjust your budget and move on. It's all about being flexible and prepared.
The important distinction is that flexibility does not mean ignoring a mismatch. If I overspend in one category, I need to choose where the money will come from rather than quietly treating the difference as harmless. That can be mildly annoying in the moment, but it is also the point: the adjustment makes the trade-off visible. I would especially recommend this approach to people who are willing to revisit their choices without turning a changed plan into a personal failure.
Where the process can break down
The main friction is consistency. If I leave purchases unreviewed or avoid changing categories after plans shift, the budget becomes less helpful because it no longer reflects what is happening. A quick check-in can keep it useful, but someone who dislikes regular financial housekeeping may find the attention demanding. I also would not choose it just to get a pretty summary of spending; a bank account overview or a basic tracker is less involved for that purpose.
There is another trade-off in choosing a method that asks me to plan actively: it can expose awkward priorities. If there is not enough money for every goal, the app cannot remove the underlying decision. It can make the options clearer, but I still have to decide what to delay, reduce, or fund differently. For couples, that works best when both people are comfortable discussing those choices. Shared visibility helps, but it cannot replace agreement about what the household values.
YNAB is rated for Everyone, has an average rating of 4.5 from around 24,000 ratings, and has been installed over a million times. The current version is 26.4.2, and it supports devices running iOS 11 or later. Those details may help with basic suitability, but I would make the decision based on the workflow: it is for someone ready to assign money, revisit the plan, and use that plan to guide everyday spending.
Who will get the most from it
I think it is a strong fit for people who want more control over variable spending, are saving toward several goals, or need a shared plan with a partner. It can also help someone who earns money at uneven intervals, provided they are comfortable prioritizing immediate needs instead of budgeting around hoped-for income. The clearest sign it may suit you is that you want to answer “Can I afford this?” by checking what the money is already meant to cover.
I would skip it if I wanted budgeting to happen almost entirely in the background, or if I only needed a quick monthly breakdown of where transactions went. In those cases, a simple tracker, an existing bank tool, or a spreadsheet may be easier and less demanding. Likewise, if the subscription cost would add stress, it makes sense to compare it with free alternatives before committing. The app’s method can be valuable, but the method only pays off when I actually use it.
Final Thoughts
In a nutshell, if you're ready to take control of your finances, YNAB is worth a shot. The app is more than just a budgeting tool; it's a philosophy that changes how you think about money. Yes, there’s a subscription fee, but I see it as an investment in my financial health. For me, the peace of mind and control over my finances is priceless.
So, whether you're a budgeting newbie or a seasoned saver, give YNAB a try. You might just find it's the financial buddy you never knew you needed!
Highlights
- User-friendly interface simplifies budgeting.
- Real-time syncing across multiple devices.
- Customizable categories for personal finance.
- Detailed reports for better financial insights.
- Effective goal-setting features keep you on track.
Limitations
- Subscription model may be pricey for some.
- Initial setup can be time-consuming.
- Limited investment tracking options.
- No direct bill payment feature available.
- Requires consistent input for best results.
Frequently Asked Questions
01What is YNAB, and how does it work?
YNAB, or You Need a Budget, is a personal finance app designed to help users manage their money effectively. It operates on a zero-based budgeting system, where every dollar is assigned a purpose. Users can link their bank accounts, track expenses, and adjust their budgets in real-time. This approach encourages mindful spending and financial planning.
02Can YNAB be used on multiple devices?
Yes, YNAB supports synchronization across multiple devices. You can use it on Android, iOS, and desktop platforms, ensuring that your budget is always up-to-date regardless of where you access it. This feature is particularly useful for couples or families managing a shared budget, allowing everyone to stay informed.
03Is my financial data safe with YNAB?
YNAB prioritizes user security with robust encryption standards and secure data handling practices. They employ bank-grade encryption to protect your information, and no sensitive data is stored on your device. YNAB also offers additional security features like two-factor authentication to enhance account protection.
04Does YNAB offer customer support if I encounter issues?
Yes, YNAB provides comprehensive customer support through various channels. Users can access help via email, live chat, and an extensive knowledge base on their website. Additionally, YNAB offers free online workshops and video tutorials to help users get the most out of the app and improve their budgeting skills.
05Is there a trial period or free version of YNAB available?
YNAB offers a 34-day free trial period, allowing users to explore its features without commitment. This trial period gives you the opportunity to fully assess whether the app meets your budgeting needs. After the trial, YNAB requires a subscription, which can be paid monthly or annually based on user preference.
YNAB in other languages


